Skip to content
Rx For Ohio

Prices checked 10/18/2026

How we check

Coverage guide · Wegovy

Can you use your HSA or FSA to pay for Wegovy?

IRS rules say yes when a doctor prescribes it to treat a diagnosed disease. The catch is in how you pay on Novo's $349 self-pay offer.

Published
Last reviewed
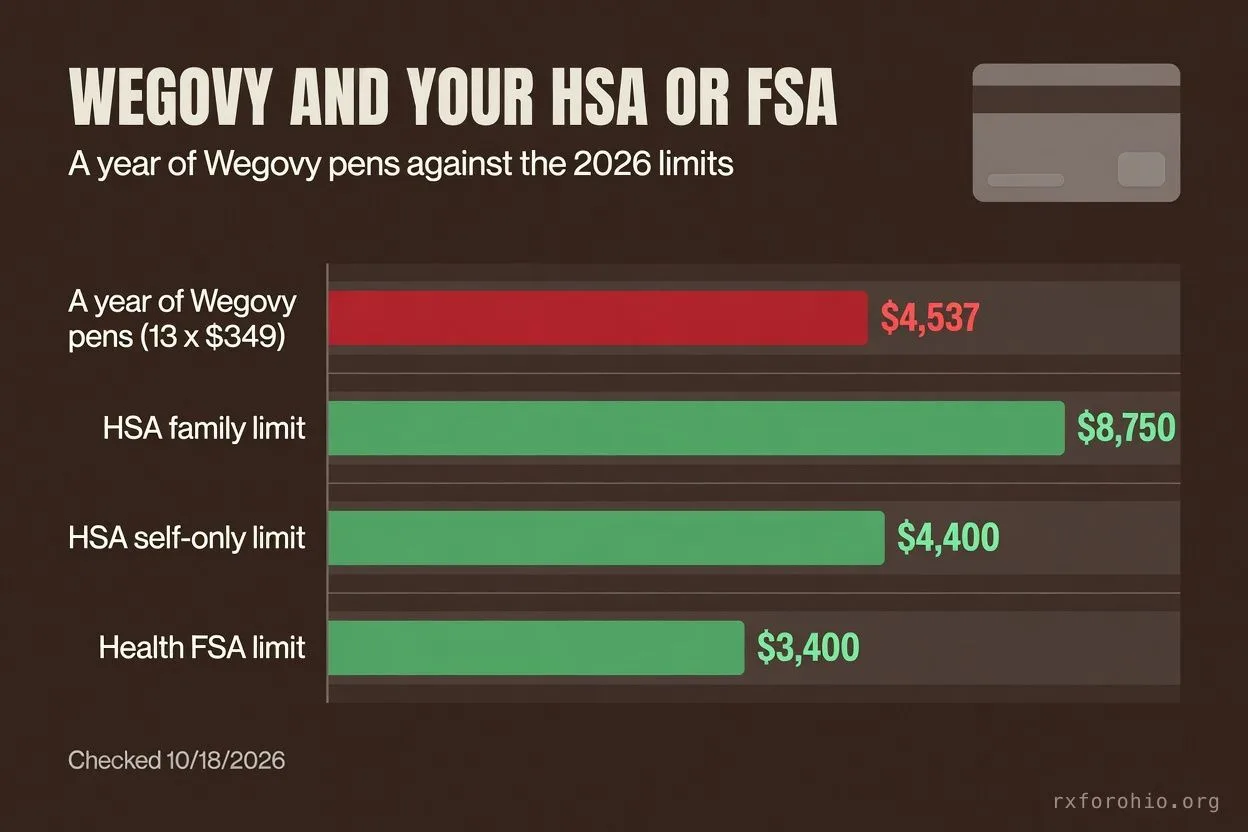
A year of Wegovy pens costs $4,537 (13 fills at $349), against 2026 limits of $8,750 for a family HSA, $4,400 for a self-only HSA and $3,400 for a health FSA.
Graphic built from the figures in this article.
Wegovy pen, self-pay price you can pay with an HSA or FSA card

$349per 28-day supply, 4 pens

Checked
10/18/2026
Source
NovoCare Pharmacy, Wegovy page (Novo Nordisk)

Can you use HSA for Wegovy? Yes, in most cases. IRS rules treat a prescribed drug as a medical expense (rules checked 10/18/2026). That includes a drug used to treat obesity diagnosed by a doctor. The same rules cover a health FSA.

The catch is how you pay. If you buy Wegovy on Novo Nordisk's self-pay offer, $349 a month for the pen, pay with the HSA or FSA card at checkout. Novo's terms rule out filing a claim afterwards. They bar claiming from a health care reimbursement account, yet NovoCare Pharmacy accepts HSA and FSA cards, so the card at checkout is the path that works.

What does the IRS say about weight-loss drugs?

The IRS doesn't name Wegovy or any GLP-1 drug. We searched both of its main publications on these accounts and found no mention. So two general rules decide it.

The first is about drugs. IRS Publication 502 says you can include in medical expenses amounts you pay for prescribed medicines and drugs. Wegovy needs a prescription, so it passes that test.

The second is about weight loss. Pub 502 counts money spent to lose weight if it is a treatment for a specific disease diagnosed by a physician (such as obesity, hypertension, or heart disease).

The IRS repeats that test in its FAQ on nutrition and wellness costs. That FAQ is written for HSAs, FSAs, Archer MSAs and HRAs, not just tax deductions. On weight-loss programs, the answer is Yes, but only if the program treats a specific disease diagnosed by a physician.

For an HSA, Publication 969 defines what you can spend on. It's medical care as the tax code defines it, but only to the extent the amounts are not compensated for by insurance or otherwise. In plain terms: the HSA can pay your share, not the part your plan already paid.

When does Wegovy qualify, and when doesn't it?

It qualifies when it treats a diagnosed disease. The FDA label approves Wegovy for people with obesity, and for adults with overweight plus at least one weight-related condition. It also covers lowering heart risk in some adults and treating a type of fatty liver disease, called MASH.

A prescription for one of those uses lines up with the IRS test. Your prescriber's diagnosis is what counts, so it helps if it's written down in your chart.

It doesn't qualify when the goal is looks. Pub 502 rules out weight-loss costs if the purpose of the weight loss is the improvement of appearance, general health, or sense of well-being.

Two more limits from Pub 502 matter here. A drug you import from another country generally doesn't count unless it came in legally. And an HSA can't pay for costs from before you opened it, per Pub 969.

Do you need a letter of medical necessity?

The IRS publications don't use that phrase for prescription drugs. What they do require is proof, and who checks it depends on the account.

HSA. No one approves an HSA withdrawal in advance. Pub 969 says you must keep records showing The distributions were exclusively to pay or reimburse qualified medical expenses. You also keep proof that nothing else paid the bill and that you didn't deduct it. You don't send these with your return.

The risk is yours if you can't back it up. Per Pub 969, money you take out for anything else is taxed as income and may owe an extra 20% tax.

Health FSA. Your employer's plan checks before it pays. Pub 969 says the FSA needs a written statement from an independent third party stating that the medical expense has been incurred and the amount of the expense. Paying with the FSA card can make this easier. If the card meets IRS proof rules, Pub 969 says you may not have to provide additional information.

So a letter isn't an IRS requirement, but your plan sets its own paperwork rules and may ask for one. Check with the administrator before you order. Either way, keep the prescription, the receipt and the diagnosis note.

How do you pay for Wegovy self-pay with an HSA or FSA card?

You pay at checkout with the card. Self-pay prices for the drugs most people ask about, checked 10/18/2026:

Self-pay prices you can pay with an HSA or FSA card at checkout. Prices per supply period.
ProductPrice
Wegovy pen0.25 to 2.4 mgper 28-day supply, 4 pens$349
Wegovy pen, intro price0.25 or 0.5 mgNew self-pay patients, first 2 fills, through 12/31/2026per 28-day supply, 4 pens$199
Wegovy pill1.5 mgper month, 30 tablets$149
Zepbound KwikPen or vials (LillyDirect)2.5 mgLilly lists it as HSA/FSA eligible, adding that eligibility may vary by planper 28-day supply$299
checked 10/18/2026
Sources for this table
NovoCare Pharmacy, Wegovy page (Novo Nordisk)Pen $349/month (0.25 to 2.4 mg); $199 intro for new patients; pill from $149; accepts credit cards, Apple Pay, Google Pay and FSA/HSA cardsChecked 10/18/2026Open: NovoCare Pharmacy, Wegovy page (Novo Nordisk)
LillyDirect, Zepbound page (Eli Lilly)KwikPen or vial 2.5 mg starting at $299/month; HSA/FSA eligible, eligibility may vary by planChecked 10/18/2026Open: LillyDirect, Zepbound page (Eli Lilly)

NovoCare Pharmacy takes the cards. Its Wegovy page answers the question directly: Yes, we accept payment from FSA/HSA funds.

What you can't do is pay another way and claim it back. Novo's self-pay terms list who you can't seek payment from. The list covers any insurer, government programs, a health care reimbursement account, and any other third-party payer.

That can look like a contradiction, since NovoCare Pharmacy takes HSA and FSA cards. The way through is the one above: pay with the card at checkout and do not file a claim afterwards.

That rules out the "pay by credit card, file a claim later" route on this offer. It matters most if your employer gives you an HRA, an account that reimburses costs you've already paid.

Lilly's direct pharmacy says much the same. LillyDirect marks the Zepbound KwikPen and vials HSA/FSA eligible and adds Eligibility may vary by plan. Its Mounjaro page carries the same note. Read Lilly's terms for any limits on claiming the cost back.

If your insurance covers Wegovy instead, your copay is a medical expense too. You can pay it with the card the same way.

Will a year of Wegovy fit in your HSA or FSA?

Probably not in an FSA. At the standard $349 per 28-day box, 13 boxes cover 364 days and cost $4,537. That's our arithmetic, not a Novo price.

A year of Wegovy pens next to the 2026 IRS limits on what you can put into an FSA or HSA.
ProductPrice
Wegovy pen, 13 fills0.25 to 2.4 mg364 days; our math: 13 x $349$4,537
Health FSA, most you can electplan years starting in 2026$3,400
HSA, most you can contribute2026, self-only HDHP coverage$4,400
HSA, most you can contribute2026, family HDHP coverage$8,750
checked 10/18/2026
Sources for this table
NovoCare Pharmacy, Wegovy page (Novo Nordisk)Pen $349/month (0.25 to 2.4 mg); $199 intro for new patients; pill from $149; accepts credit cards, Apple Pay, Google Pay and FSA/HSA cardsChecked 10/18/2026Open: NovoCare Pharmacy, Wegovy page (Novo Nordisk)
IRS Publication 15-B (2026)For plan years beginning in 2026, health FSA salary reduction contributions are capped at $3,400Checked 10/18/2026Open: IRS Publication 15-B (2026)
IRS Publication 969 (2025)For 2026, HSA contributions up to $4,400 with self-only HDHP coverage and $8,750 with family coverageChecked 10/18/2026Open: IRS Publication 969 (2025)

The 2026 health FSA limit is $3,400 per plan year, so an FSA alone can't cover a full year of pens at $349. An HSA has more room: $4,400 for self-only coverage in 2026, per Pub 969. That limit has to cover every medical bill you have, unless you saved HSA money in earlier years.

The cheaper forms change the math. The 1.5 mg Wegovy pill is $149 a month, or $1,788 for 12 bottles by our count. Which form or strength you take is your prescriber's decision, not a budget one.

Can you deduct Wegovy on your taxes instead?

You can, if you itemize and your costs are large enough. Pub 502 says you can deduct only the part of your medical costs that is more than 7.5% of your AGI. AGI means adjusted gross income.

You can't use the same dollars twice. Pub 502 says you can't include expenses you pay for with a tax-free distribution from your health savings account. The same goes for costs your FSA fully paid back.

One note if you're on Medicare: per Pub 969, your HSA contribution limit drops to zero starting the first month you're enrolled.

Before you pay

  1. Make sure the prescription is for a diagnosed condition, such as obesity or a weight-related disease. The IRS doesn't count weight loss for looks or general health.
  2. Paying Novo's self-pay price? Swipe the HSA or FSA card at checkout. Novo's terms bar claiming the cost back later from a health care reimbursement account.
  3. Keep the pharmacy receipt and the prescription. For an HSA, the IRS puts the job of proving each withdrawal on you.
  4. Ask your FSA administrator what it needs before you buy. Some plans want more than a receipt.
  5. Add up a full year before you choose your next FSA election. At $349 a box, 13 boxes cost $4,537, more than the 2026 FSA limit of $3,400.
  6. Don't count the same dollars twice. Anything paid from an HSA or FSA can't also go on Schedule A.

How we checked these rules and prices

We read the IRS publications and FAQ, the FDA label, and the Novo and Lilly pages on 10/18/2026. The tables above list each source and the date. If a rule or price changes, we'll date the correction here. For the full price breakdown, see our Wegovy price check. If your plan denied coverage, our guide on how to appeal a GLP-1 insurance denial walks through the steps.

This page explains the rules. It isn't tax advice, so check with your plan administrator or a tax professional for your own situation.